
Rate Rebel logo

VA Home Loans · San Diego County

You Earned This Benefit. Let's Put It to Work.

I'm Sophia Warner, and I help service members, veterans, and military families from Pendleton to Point Loma understand exactly how their VA loan works — in plain English, with no pressure.

A few quick questions. No obligation.

See How It Works

21 Years Lending

San Diego Based

Sophia Warner, Senior Loan Officer at Rate Rebel

Sophia Warner

Senior Loan Officer · Rate Rebel · NMLS# 282856

No down payment

For eligible buyers with full entitlement.

No monthly PMI

Not now, not ever, on a VA loan.

Reusable for life

It's not a one-time benefit.

The VA Loan, Explained

Two big advantages, in plain English

Most people have heard "VA loans are a good deal." Here's what actually makes them different from a regular mortgage.

No down payment required

If you have your full VA entitlement, the VA doesn't require a down payment — and there's no VA loan limit capping how much you can borrow. Instead of saving for years, you can put that money toward closing costs, moving expenses, or your emergency fund.

  • You still need to qualify based on income, credit, and debts.
  • The home has to appraise at or above the purchase price.
  • If part of your entitlement is tied up in another loan, a down payment may be needed.
No monthly mortgage insurance

With most conventional loans, putting down less than 20% means paying private mortgage insurance (PMI) every month. FHA loans carry their own monthly mortgage insurance, too. VA loans don't have any.

That's because the VA backs part of your loan — it's a VA-guaranteed loan — which protects the lender. You don't pay a monthly premium for that protection. That can make a real difference in what your monthly payment looks like over the life of the loan.

The Funding Fee

The one fee worth understanding up front

The VA funding fee is a one-time charge paid to the VA. It helps keep the program running for future service members, and it's what makes no-down-payment, no-PMI lending possible.

It's a percentage of your loan amount, and it depends on two things: whether this is your first VA loan and how much you put down. You can pay it at closing or roll it into the loan.

You may not owe it at all

  • Veterans receiving VA compensation for a service-connected disability
  • Those eligible for disability compensation but receiving retirement or active-duty pay instead
  • Active-duty members with a proposed or memorandum disability rating before closing
  • Active-duty Purple Heart recipients
  • Surviving spouses receiving Dependency and Indemnity Compensation (DIC)

If you're awarded disability compensation after closing with an effective date before closing, you may be able to request a refund.

Purchase loan funding fee schedule

Percentage of the loan amount, per the VA's current schedule

Down payment

First use

After first use

  • Less than 5%2.15%3.3%
  • 5% to under 10%1.5%1.5%
  • 10% or more1.25%1.25%

The VA sets these figures and can change them. Refinances follow a different schedule. I'll confirm your exact fee — or your exemption — before you commit to anything.

Find out if you're exempt. No commitment required.

Certificate of Eligibility

Your COE is your entry ticket

The Certificate of Eligibility is the VA's official confirmation that you've earned the home loan benefit — and how much entitlement you have available. Lenders need it before closing.

01

Through your lender

The easiest route. I can often request your COE electronically through the VA's lender system — usually in a single sitting.

02

Online at VA.gov

You can sign in to VA.gov and request it yourself. Many people get it back quickly; some cases need extra documentation.

03

By mail

Submit VA Form 26-1880 with your service documents. It works, but it's the slowest of the three options.

What you'll typically need

  • Veterans: your DD-214
  • Active duty: a statement of service signed by your commander, adjutant, or personnel officer
  • Guard & Reserve: retirement points statement or NGB Form 22, depending on your status
  • Surviving spouses: documentation varies — I'll walk you through it

I'll handle the paperwork side. No cost to ask.

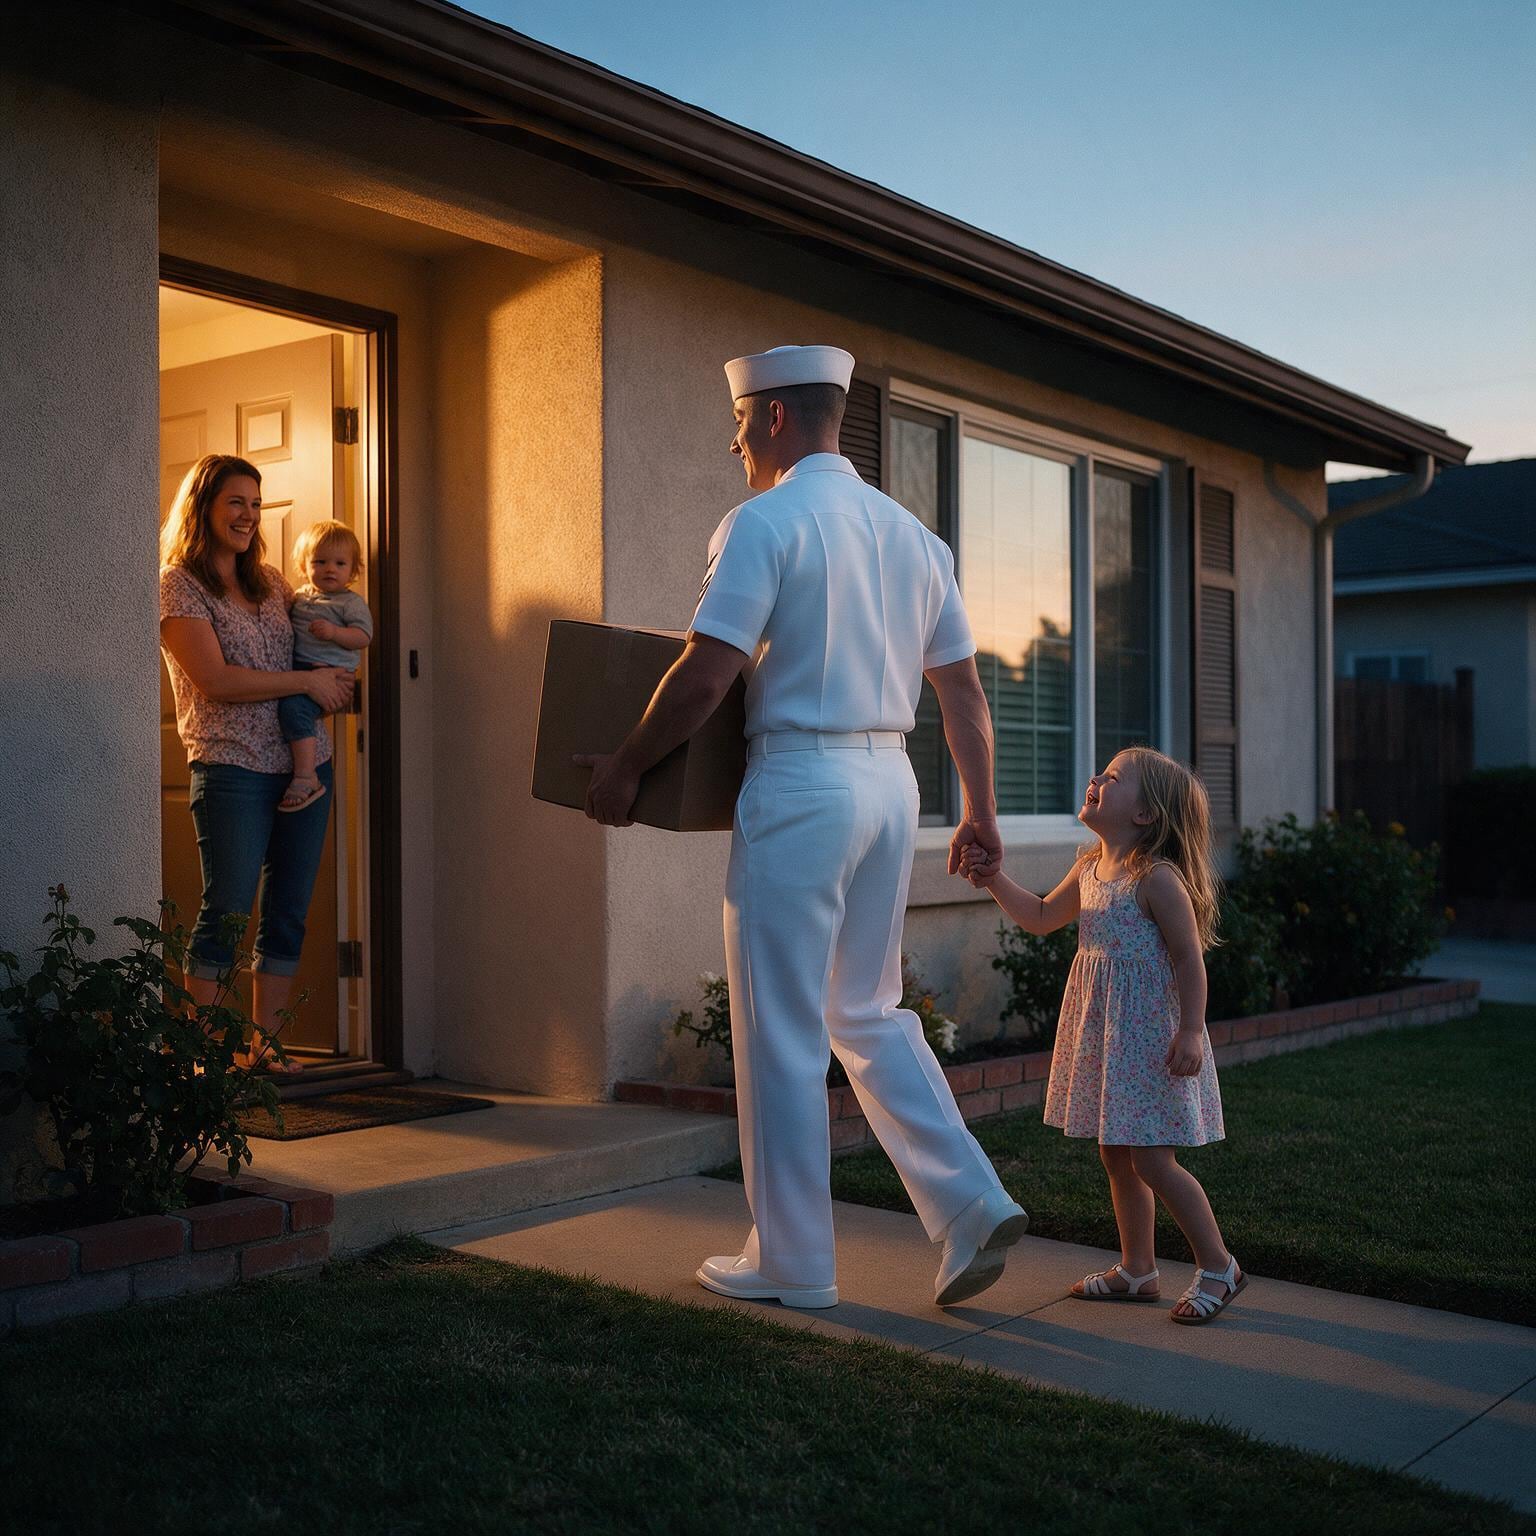
Navy sailor carrying a moving box into the family’s new San Diego home, holding his daughter’s hand

PCS orders? Growing family?

Your benefit can move with you.

Using It Again

A VA loan isn't a one-and-done benefit

Military life means moving. The good news: you can use your VA home loan benefit again and again over your lifetime. Here's how it works.

  • Sell and restoreWhen you sell your home and pay off the VA loan, you can have your full entitlement restored and use it on the next home.
  • Keep one, buy anotherMoving to a new duty station but want to keep your current home as a rental? Remaining entitlement may let you buy again while your first VA loan stays in place.
  • Paid off but still own itIf you've paid off a VA loan and kept the home, you can request a one-time restoration of your entitlement.

Keep in mind: each VA purchase must be for a home you'll live in as your primary residence, and the funding fee is typically higher after first use unless you're exempt.

Sophia Warner

Meet Your Loan Officer

Sophia Warner

Senior Loan Officer · Rate Rebel · NMLS# 282856

"Over the years, I've watched the exact same financial situation get approved by one lender and turned down by another. That's why I don't stop at one answer."

I've been in mortgage lending for 21 years, here in San Diego. Banks work inside strict rules, but I have access to a network of lenders with different criteria — which means I can often find a path for clients that a traditional bank might not.

For military families, that matters. Deployments, PCS moves, BAH, a spouse's income that changes with every duty station — your situation isn't "standard," and it shouldn't have to be. My job is to explain every piece of your VA loan clearly, so you can make the call that's right for your family.

No pressure. Just straight answers.

(619) 886-6985

Common Questions

What military buyers ask me most

Who is eligible for a VA loan?

Most veterans, active-duty service members, and National Guard and Reserve members who meet the VA's minimum service requirements are eligible, along with some surviving spouses. The exact requirement depends on when and how you served — your Certificate of Eligibility confirms it.

Can I buy while I'm deployed or before I PCS?

Often, yes. The VA requires that you intend to live in the home as your primary residence, but if you're deployed, a spouse living in the home can satisfy the occupancy requirement. Buying ahead of PCS orders to San Diego is common too — we'll plan the timing around your report date.

Does no down payment mean no money at closing?

Not necessarily. There are still closing costs like appraisal, title, and escrow fees. Some of those can be covered by seller concessions or rolled in where allowed, and the funding fee can be financed. I'll give you a clear estimate early so nothing catches you off guard.

Can I use BAH as income?

Allowances like BAH can generally be counted as income when qualifying, which can make a meaningful difference in high-cost areas like San Diego County. How it's counted depends on your situation, so we'll review your Leave and Earnings Statement together.

Will checking my eligibility affect my credit?

Filling out the short eligibility form doesn't pull your credit. It simply gives me enough information to reach out and talk through your options. If you decide to move forward later, I'll always tell you before any credit check happens.

What Happens Next

You're Closer Than You Think

Checking your eligibility takes a couple of minutes. From there, it's a real conversation with a real person — me.

Answer a few questions

Service status, timeline, and where you're hoping to buy. That's it.

I personally follow up

I'll reach out by phone or email — whichever works around your schedule.

We confirm your benefit

I help you get your COE and check whether you're exempt from the funding fee.

You decide

You'll see your options laid out clearly. Moving forward is entirely your call.

No credit pull. No obligation. Just clarity.

Prefer to talk now? Call (619) 886-6985

Powered byrebel iQ